Hot Products
Popular articles
How can third-party enterprise content move from brand mention to partner co-creation? GEO collaboration among distributors, integrators, and OEM customers.
Before Thanksgiving, Overseas Buyers Need to Confirm Not Discounts, but Whether You Can Still Deliver
Recommended Reading

If you want to adjust the GEO budget based on the performance of different countries, how do you set the calculation method for regional ROI, including input allocation, revenue or gross profit, and exchange rate?
In response to the need to adjust GEO budgets based on country performance, AB Customer has compiled a list of shared investment allocations, revenue or gross profit, transaction attribution, accounting cycle, and exchange rate standards that need to be confirmed by both parties before calculating regional ROI. It also explains the data foundation that CRM and AI sales assistants can provide, as well as the results that cannot be calculated or are not suitable for comparison when data is missing.
First, agree on the accounting rules, then adjust the GEO budget according to the country.
When comparing the input and output of GEO (Georgia O2O) projects by country, it's not enough to simply look at which market has more inquiries. It's necessary to confirm first.How should regions be divided, how should investments be allocated, should revenue be used or gross profit be used, how should transactions be attributed, and how should accounting cycles and exchange rates be standardized?Then determine which results can be calculated and which can only be used as process references.
ABKEThe CRM and AI sales assistant can record lead, inquiry, opportunity, follow-up and transaction information, providing a data foundation for lead quality and sales process analysis in different countries.The existing product data is insufficient to confirm that it has a complete regional ROI calculation capability.The calculation of costs, financial benefits, exchange rates and attribution needs to be confirmed separately by both parties, and the rules and data responsibilities cannot be assumed to be completed automatically by the system.
I. What criteria need to be confirmed before calculating regional ROI?
It is recommended that a mutually agreed-upon accounting caliber table be prepared before the assessment, and a copy be retained. In the event of an adjustment to the accounting caliber, the effective date and whether historical results are recalculated should be specified to avoid the application of different rules to the same country over time.
| Accounting items | Content to be confirmed by both parties | Mixing that needs to be avoided |
|---|---|---|
| National Affiliation | It should be attributed according to agreed rules such as the country where the client company is located, the country where the procuring entity is located, or the delivery market; and it should be clearly defined how to handle multinational clients. | The country of the accessed IP address and the page language are directly equated with the country of the transaction. |
| Scope of Investment | List the costs for included services, content, websites, channels, and internal personnel, and differentiate between direct regional investments and shared investments. | It only records the direct costs of a certain country, but calculates the return using revenue that includes contributions from shared assets. |
| Definition of revenue | Choose between revenue or gross profit, and confirm the processing method for orders, revenue recognition, payment collection, refunds, and allowances. | Treat the quoted amount and the estimated amount of the business opportunity as realized revenue. |
| Transaction Attribution | Identify the attribution targets, touchpoint rules, observation windows, and the handling of new customer purchases, repeat purchases from existing customers, and transactions from multiple channels. | Attributing all regional transactions to GEO contribution, or repeatedly counting the same order across multiple channels. |
| Cycles and exchange rates | Confirm the period covered by input and output, unify the accounting currency, the source of exchange rate, the conversion time, and the handling of exchange differences. | Divide this month's investment by the historical transaction amount, or arbitrarily select different exchange rate points for different countries. |
| Data responsibility | Clearly define which data each of the marketing, sales, and finance departments should provide, review, and supplement. | Treating missing data as zero, or using AI inferences as financial confirmations. |
II. How should shared costs be allocated to facilitate comparisons between countries?
GEO websites, corporate knowledge bases, multilingual content, and channel operations may serve multiple countries. Regional costs should consider both direct and shared inputs; the absence of separate cost breakdowns for a particular country does not preclude the assumption of no costs.
-
First, identify direct inputs:For projects that can be clearly attributed to a specific national market, they should be grouped according to actual records.
-
Next, determine the shared fee pool:Distinguish between websites, knowledge, content, and operating costs that are reused across markets to determine which fall within the scope of this assessment.
-
Choose a well-founded allocation rule:The apportionment can be discussed based on agreed workload, resource usage, or budget ratio, but there must be verifiable evidence and consistency must be maintained within the same assessment period.
-
Treat long-term asset investments separately:Whether expenses for website construction and knowledge base setup are recorded in the current period or amortized over several periods should be consistent with the company's financial reporting standards to avoid double-counting.
It's inappropriate to automatically allocate more costs to a particular country simply because it receives more inquiries, and then use the resulting ROI to determine the budget. If traffic or lead ratios are used for cost allocation, their limitations should be explained, and if necessary, the results should be compared with other reasonable rules to check for significant changes.
III. What questions do revenue, gross profit, and ROI answer respectively?
Revenue reflects business scale, while gross profit more closely reflects the contribution after deducting product-related costs; neither is equivalent to final net profit. It is recommended to prioritize clearly defining the names and formulas of the metrics, rather than collectively referring to all input-output indicators as ROI.
Income-to-Input Ratio
Regional attributable income ÷ Regional GEO input
This is used to observe the revenue corresponding to each unit of input, and does not represent profit return. Revenue must first be confirmed, refunded, discounted, and taxed in a unified manner.
Regional ROI based on gross profit
(Regional attributable gross profit - Regional GEO input) ÷ Regional GEO input
This definition should only be used when both parties adopt it, the input is greater than zero, and the data is complete. Cost items in gross profit must be clearly defined; previously deducted GEO expenses cannot be deducted again.
If both parties choose to use a revenue-based ROI, the formula and its expression should be clearly defined.Does not reflect product costs and net profitThere are limitations. Regardless of the metric used, attributable revenue must have agreed-upon attribution criteria and cannot be directly applied to all sales revenue of a particular country.
IV. The attribution of transactions, the accounting period, and the exchange rate need to be determined together.
Multi-touchpoint sales: Differentiating between "leads" and "opportunities"
Customers may read the content first, then contact the company through social media channels, with the salesperson ultimately driving the sale. It's essential to agree on first-touchpoint, last-touchpoint, or other allocation rules, and to differentiate between source attribution and content impact analysis. Having access to the content does not necessarily mean the sale was entirely driven by the GEO; when the source is unidentifiable, it should be left as "unknown" rather than being forcibly categorized.
Long sales cycle: Differentiate between current performance and lead batch performance
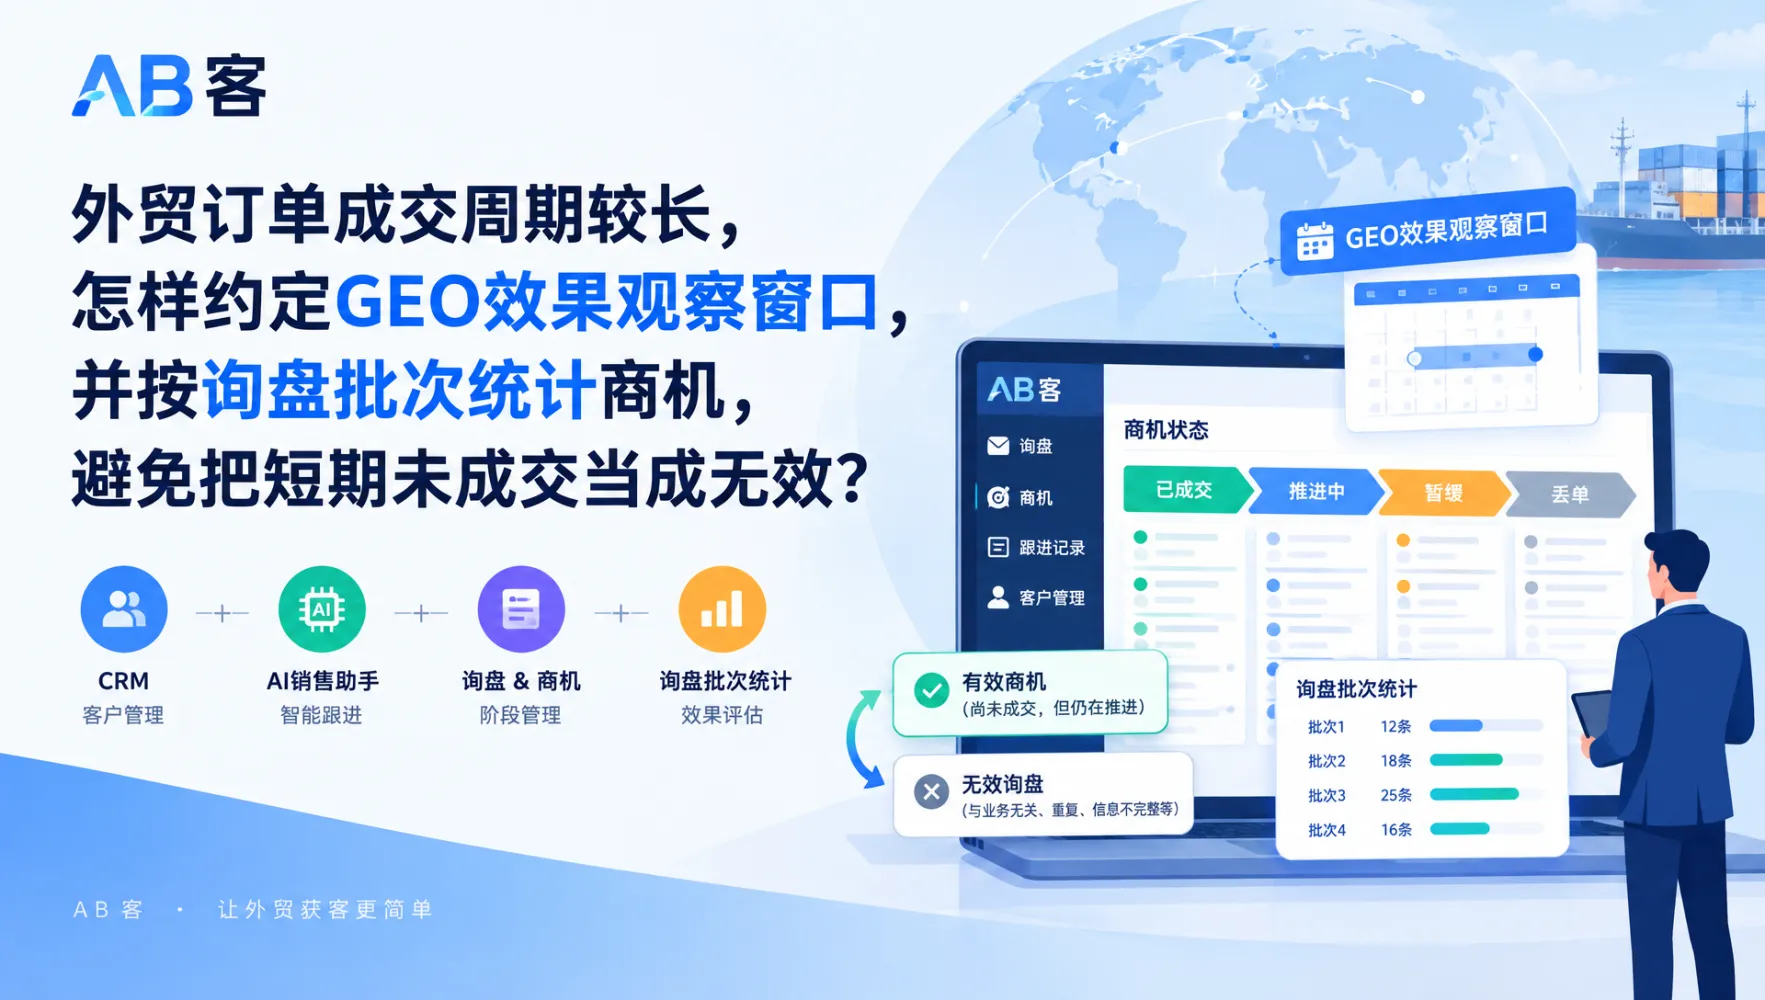
Foreign trade B2B business opportunities may be transacted across timeframes. Observing by calendar month or quarter is suitable for understanding the current operating situation; continuously tracking leads that entered during the same period is more helpful for comparing subsequent conversions. The two types of reports should not be used interchangeably, nor should new markets that have not been fully followed be directly ranked with markets where customers have been accumulated for many years.
Multi-currency services: Retain the original currency and unify the conversion rules.
It is recommended to retain the original currency amount, currency type, and business date, and separately agree on a unified accounting currency and exchange rate source. The exchange rate used should match the selected revenue caliber, based on the transaction date, revenue recognition date, payment receipt date, or average exchange rate over the period, and it should be explained whether the exchange rate difference is listed separately. If it is necessary to observe market performance excluding exchange rate fluctuations, a fixed exchange rate can be used for comparison, but it should not be confused with the actual conversion result as the same indicator.
Related reading:
V. What data foundations do CRM and AI sales assistants provide?
AB Customer CRM and AI Sales AssistantThe responsibility isLead generation, sales coordination and operational feedbackThis connects front-end content, website, and channel touchpoints to the back-end follow-up process.
-
Customer and source records:Organize customer information, contact information, inquiry sources and content, and channel touchpoints to retain basic information for regional analysis.
-
Inquiry quality and business opportunity process:Record A/B/C category and invalid inquiries, opportunity stages, follow-ups, quotations and transaction information, and distinguish between "many inquiries" and "many valid opportunities".
-
AI-assisted sales:Based on enterprise knowledge and customer information, it assists in inquiry summarization, intent identification, quality stratification, response preparation, material recommendation, and sales review; the judgment results still need to be verified by sales personnel.
-
Market feedback:Analyze lead quality across different countries, languages, pages, and channels by combining sales feedback to inform budget discussions.
Cost ledgers, gross profit confirmation, financial reconciliation, currency conversion, and complete regional ROI reports should not be considered standard functions simply because a CRM system has transaction records. Required fields, data relationships, reporting methods, and implementation scope need to be verified and confirmed separately.
VI. When data is missing, which results cannot be calculated?
-
Lack of regional investment or cost sharing:It cannot calculate the ROI of the entire region; even if there is revenue, only revenue data can be displayed first.
-
Missing attributable transaction or revenue amount:Regional GEO revenue and full ROI cannot be calculated. Valid inquiries, A/B category ratio, and number of business opportunities can only be used as process indicators.
-
Product cost or gross profit data is missing:ROI based on gross profit cannot be calculated; if other conditions are met, the clearly marked revenue-to-investment ratio can be displayed separately.
-
Lack of reliable national affiliation:The relevant transactions cannot be accurately attributed to a specific country, nor should they be used to rank countries.
-
Lack of a unified cycle, currency, or exchange rate:Results from relevant markets should not be directly compared; a unified standard should be established first.
-
Lack of follow-up and business opportunity feedback:The subsequent value of clues cannot be reliably determined; no record does not mean no transaction or market inefficiency.
-
Investment is zero or has not yet been confirmed:ROI ratios are undefined or uncalculated and should not be displayed as "unlimited returns".
Key differences:It has been verified that no transaction was completed, which is different from the situation where transaction data has not yet been returned. Only the former, when all other conditions are met, can be included in the calculation as a confirmed zero profit; the latter should be marked as missing data.
Make budget adjustments based on verifiable operational data.
It is recommended that the marketing manager first confirm the input and source records, the sales manager confirm the lead quality, opportunities, and sales, and the finance manager confirm revenue, gross profit, and exchange rates, and then jointly review the regional results. For countries with incomplete data or where the sales cycle is not yet mature, a list of data supplementation tasks and observation points should be compiled first, rather than deciding on budget adjustments solely based on the number of inquiries.
When discussing adjusting the GEO budget by country with AB clients, you can first prepare a list of target countries, investment details, client country affiliation, lead and opportunity records, transaction and financial data, and then confirm.The indicators that can be directly analyzed, the data that needs to be supplemented, and the accounting work that needs to be agreed upon separately.CRM and AI sales assistants help record and make judgments, but they do not replace sales business judgment, nor do they guarantee fixed inquiries, sales, or return on investment.


