Hot Products
Popular articles
广交会前48小时怎么做GEO?用7项优先级清单完善官网与询盘入口
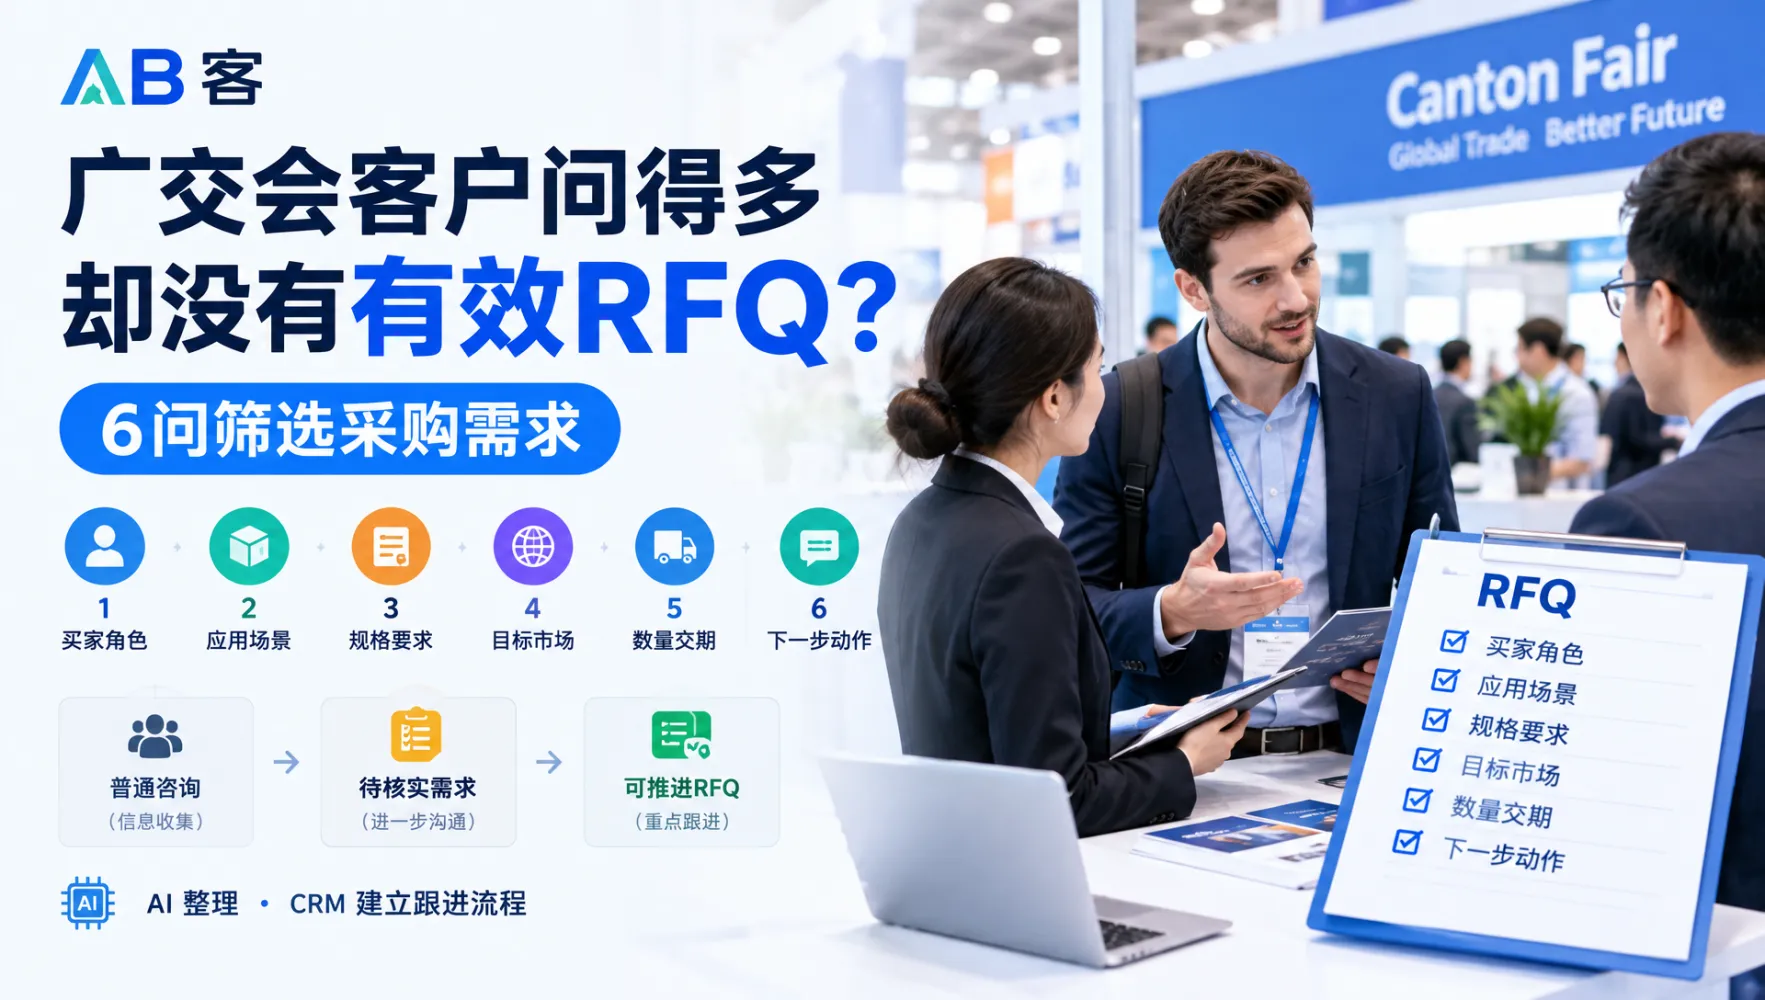
广交会客户筛选实操指南:用6个问题识别采购需求,推动有效RFQ
广交会后五金工具企业GEO指南:用采购决策内容减少单纯比价
Recommended Reading
Can ABKE GEO Costs and Separate Ad Tests Fit Within Our Budget?
Assess ABKE GEO costs alongside separate ad tests using a complete cost framework, budget scenarios and loss limits. Confirm modeling and ad service scope first.
Confirm the Service Scope Before Assessing Budget Affordability
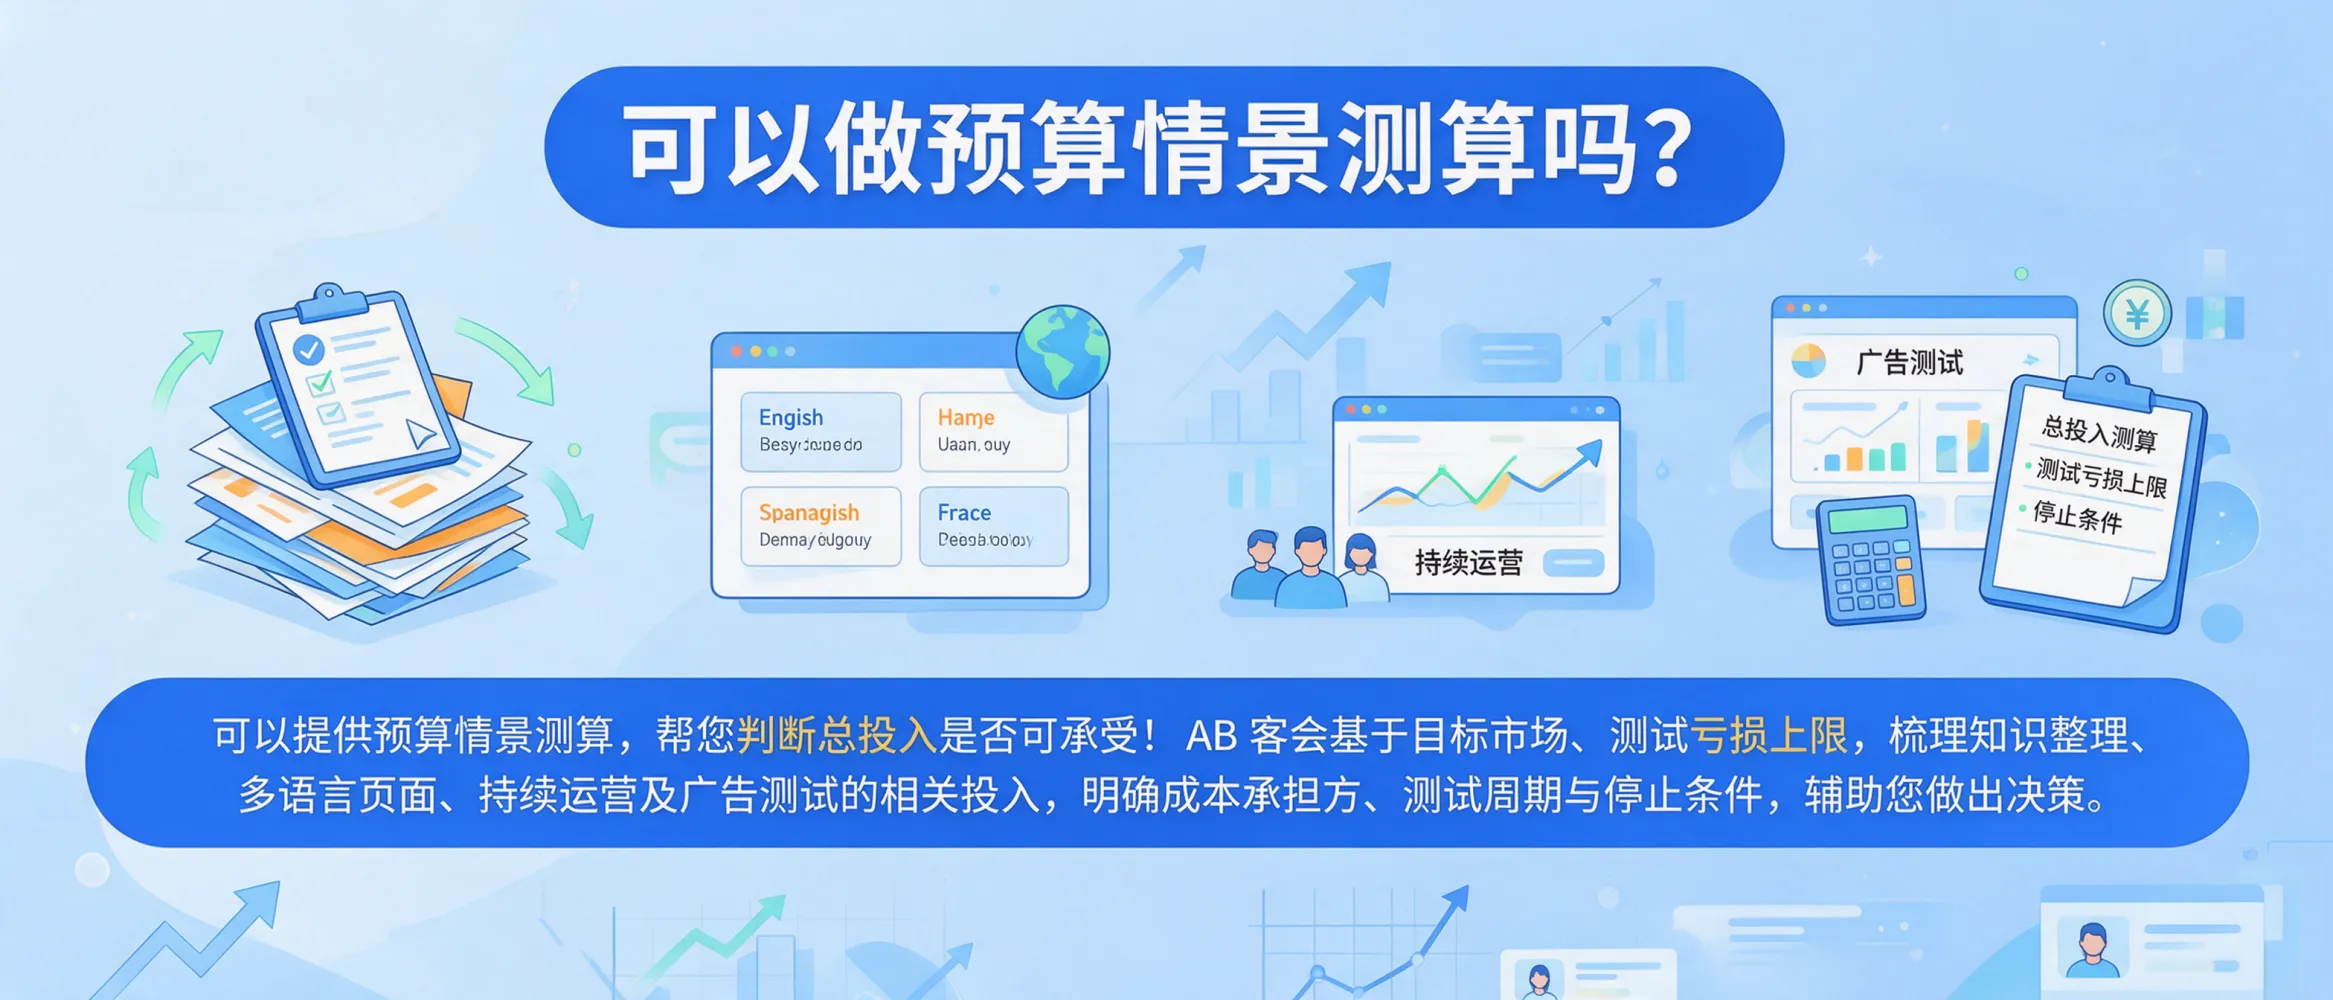
Providing your target markets and acceptable test loss limit helps establish a budget assessment framework, but it does not establish that ABKE provides budget scenario modeling or advertising management. The documented scope of the ABKE GEO Growth Engine covers enterprise knowledge management, multilingual content, website development, ongoing operations and data analysis. Dedicated financial modeling, advertising account setup, campaign execution and advertising attribution support must each be confirmed and included in the agreed scope of work.
Even if AI platforms such as ChatGPT expand advertising availability, this does not mean that your target country, industry, account or landing page is eligible. It also does not provide a basis for assuming customer acquisition costs.
1. List All Costs Over the Same Evaluation Period
Use a mutually agreed test period and distinguish one-time, recurring and optional expenses:
- Setup costs: Knowledge organization, product information structuring, multilingual pages, website setup and conversion-path configuration.
- Ongoing operating costs: Content updates, localization reviews, channel operations, monitoring and optimization.
- Advertising test costs: Media spend, plus any separately charged creative production, landing pages, agency services and tracking configuration.
- Internal and third-party costs: Product expert reviews, sales follow-up, translation and other supporting resources.
For every item, specify whether it is included in ABKE’s quotation, who performs the work and who pays. This helps prevent duplicate charges and overlooked expenses.
2. Separate Total Investment From Test Losses
Total investment is not the same as the test loss limit. Knowledge bases and websites may become long-term assets, but they still consume cash during the evaluation period. The accounting scope for test losses must be agreed in advance.
If test losses are calculated as test expenses minus contribution margin from attributed orders, define how refunds, fulfillment costs, payment timing and the attribution window will be treated.
B2B sales cycles can be lengthy. Unconverted inquiries and projected order values must not be treated as recovered cash.
3. Use Scenario Ranges Rather Than Single-Point Promises
Conservative, baseline and optimistic scenarios can be used to state assumptions for:
- Advertising unit costs
- Qualified inquiry rates
- Sales conversion rates
- Order contribution margins
- Payment collection cycles
Where historical data is unavailable, label these figures as assumptions requiring validation. Start with a small test and adjust the budget based on the findings, rather than promising a fixed number of inquiries or sales.
4. Put Stop Conditions Into the Execution Plan
Alongside the cumulative loss limit, establish a cash spending cap, phased approval limits and pause conditions. These may include:
- Tracking failures
- Cost per qualified inquiry exceeding the agreed limit
- Lead quality consistently falling below the agreed standard
The final decision should consider three questions together: Can you absorb the worst-case scenario? Can your cash flow support the plan? Are the long-term assets worth retaining?
Start by providing your target countries, product margins, historical conversion data, payment collection cycles, budget and test loss limit. Each execution party should then confirm its quotation, responsibility for scenario modeling and agreed stop-loss mechanisms.


